ACTUARIAL CASH-FLOW SIMULATION ENGINE
VUE 3 · FASTAPI · DOCKER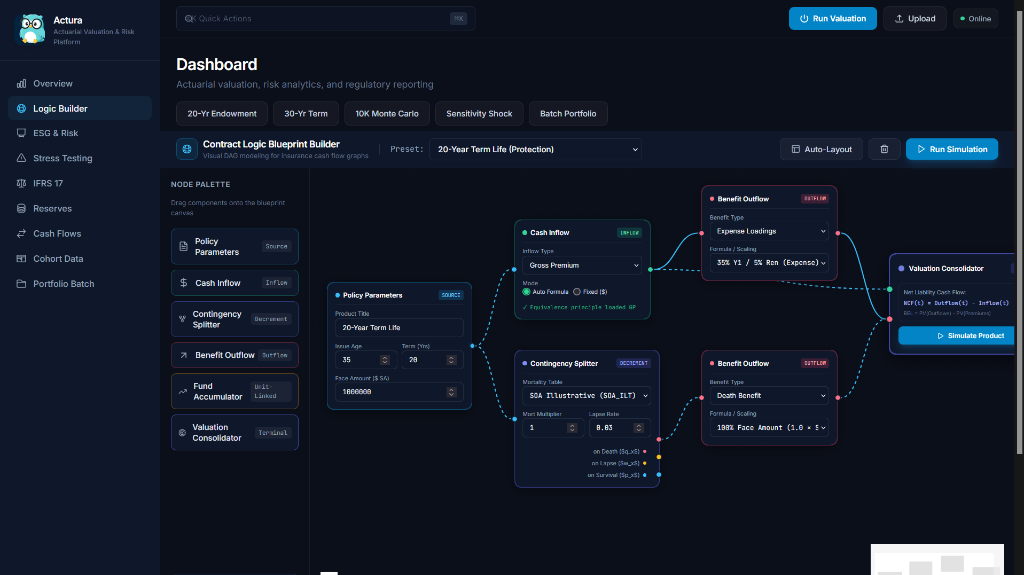
FLAGSHIP · SOLO PROJECT· 2026
Actura
Values life-insurance liabilities two ways: a deterministic run projects the Best Estimate Liability (BEL) under fixed best-estimate assumptions, and a Monte Carlo run evaluates cash flows across stochastic interest-rate scenarios to produce a liability distribution with VaR / CVaR.
10,000 Monte Carlo paths in 0.07 s · 10,000-policy portfolio valuation in 0.12 s (Ryzen 7 7735HS)
What I built (solo): the FastAPI valuation and DAG execution engine, the Vue 3 / Vue Flow logic workbench with ECharts visualizations, and the Docker setup.